Contents:
- Intro Question
- Brief Answer
- Why These Fees Exist
- Quick Answer for Skimmers
- Seasonal Timeline Consideration
- When It Applies
- When It Doesn’t Apply
- Common Processor Comparison
- Common Mistakes to Avoid
- FAQ
- Can I pass processing fees to customers?
- Why do rewards cards cost merchants more?
- Is Square or Stripe cheaper for small businesses?
- Conclusion
- Personal Anecdote
- What the Pros Know
Nearly 30% of small business owners admit they don’t fully understand their own credit card processing statement, according to recent small business banking surveys, and that confusion often costs real money every month.
Intro Question
What should small business owners actually expect to pay for credit card processing, and where do the hidden costs typically hide?
Brief Answer
Credit card processing fees generally run 1.5% to 3.5% per transaction, combining interchange fees, assessment fees, and processor markup, with exact rates depending on card type and your chosen provider.
Why These Fees Exist
Interchange fees go to the customer’s card-issuing bank, assessment fees go to networks like Visa or Mastercard, and the remaining markup covers your processor’s service and profit margin.
Quick Answer for Skimmers
Debit cards typically cost less to process than credit cards, and rewards credit cards cost more than standard cards, since card issuers charge higher interchange rates to fund those rewards programs.
Seasonal Timeline Consideration
Processing volume and fee totals often spike during Q4 holiday shopping, making November and December the months when small businesses most acutely feel the cumulative weight of processing percentages.
When It Applies
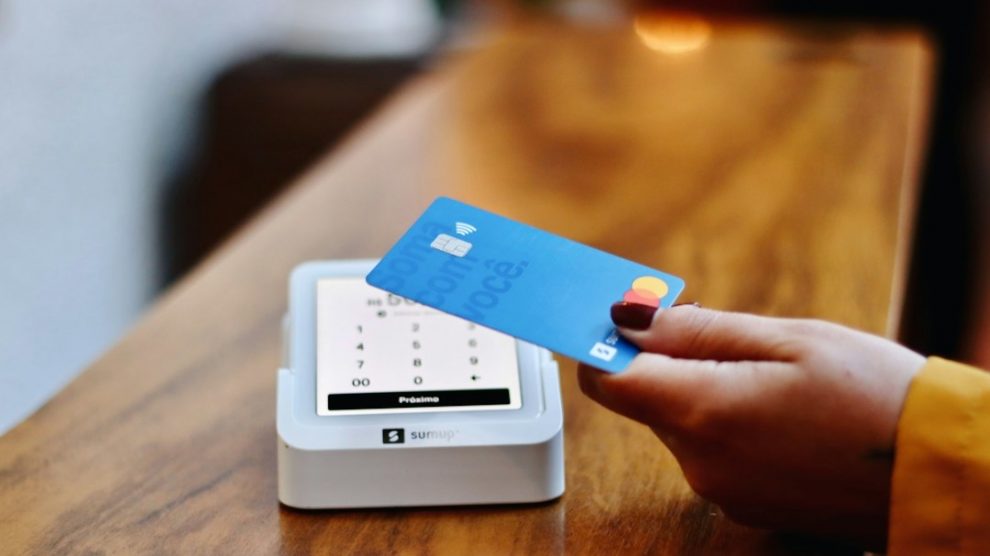
Every business accepting credit or debit cards pays some form of processing fee, whether through a traditional merchant account, Square, Stripe, or another payment platform.
When It Doesn’t Apply
Cash-only businesses avoid these fees entirely, though doing so also means losing sales from customers who exclusively prefer or only carry card payment methods in 2026’s increasingly cashless retail environment.
Common Processor Comparison
Square: flat 2.6% + $0.10 per swipe. Stripe: 2.9% + $0.30 online. Traditional merchant accounts: often 1.5-2.5% plus monthly fees, sometimes cheaper for high-volume businesses despite added complexity.
Common Mistakes to Avoid
Not comparing multiple processors before committing, ignoring monthly minimum fees buried in contracts, and failing to negotiate rates once transaction volume grows significantly beyond initial estimates.
FAQ
Can I pass processing fees to customers?
Yes, surcharging is legal in most states, though rules vary, and some states cap the surcharge amount or prohibit it entirely for debit transactions.
Why do rewards cards cost merchants more?
Card issuers charge higher interchange rates on rewards cards to help fund the cashback or points programs offered to cardholders.
Is Square or Stripe cheaper for small businesses?
It depends on transaction volume and type; in-person sellers often prefer Square, while online-focused businesses often find Stripe’s integration advantages worthwhile.
Conclusion
Understanding exactly how processing fees are structured empowers small business owners to negotiate better rates and choose processors that genuinely match their specific sales patterns.
Personal Anecdote
A boutique owner in Las Vegas switched processors after realizing her original provider’s hidden monthly minimum fee was costing her an extra $400 annually beyond the advertised per-transaction rate.
What the Pros Know
Experienced merchants recommend requesting a full fee schedule in writing before signing any processor agreement, since verbal quotes often omit smaller recurring charges that add up significantly.